Mining Chemicals Market Benchmarking Report
Report Overview:
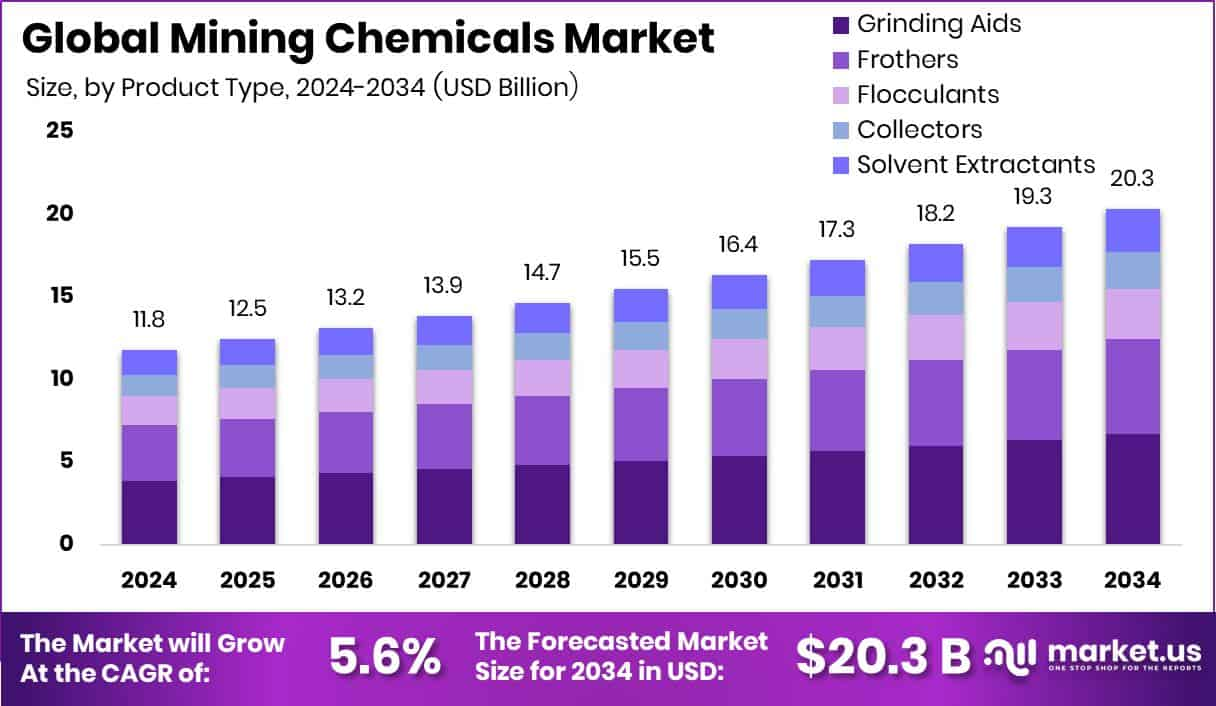
The Global Mining Chemicals Market is set to rise significantly, growing from USD 11.8 billion in 2024 to around USD 20.3 billion by 2034, registering a steady CAGR of 5.6%. Mining chemicals such as frothers, collectors, grinding aids, and flocculants play a vital role in extracting and refining minerals. Among applications, mineral processing leads the way, accounting for over 48% of the demand. Base metals are the most commonly processed minerals, contributing to 43.7% of overall usage. Grinding aids also take a strong share, making up nearly one-third of the market. The Asia-Pacific region, especially countries like China and India, dominates due to large scale mining operations and increasing industrialization. The demand for advanced chemicals is being driven by the need for higher mineral recovery, efficient processes, and better environmental performance, particularly in regions where mining is expanding rapidly or becoming more complex due to declining ore quality.
As ore quality decreases and mining operations move deeper underground, the demand for effective and specialized mining chemicals is rising. These chemicals improve recovery rates, cut down processing costs, and reduce environmental impact. Industries like construction, electronics, and automotive are consuming more metals, which in turn boosts the need for mineral extraction chemicals. Strategic moves are being seen across the sector—like Orica’s acquisition of Cyanco to enhance portfolios and enter new regional markets. Asia-Pacific remains at the forefront of this market due to ongoing industrial activity and vast mineral reserves. Countries in this region benefit from both production and consumption of mining chemicals. As the market becomes more competitive, innovation and tailored solutions are gaining traction, especially for complex ores. The use of digital systems and automation in chemical dosing is also on the rise, helping companies to streamline operations while ensuring safety and sustainability in mining activities.
Key Takeaways
The mining chemicals market is projected to grow from USD 11.8 billion in 2024 to USD 20.3 billion by 2034 at a CAGR of 5.6%.
Grinding aids are the top-selling product, holding a 32.9% market share.
Mineral processing is the leading application segment with 48.1% of the market share.
Base metals are the most processed minerals, contributing 43.7% of the chemical demand.
Asia-Pacific leads regionally with a 38.3% market share, driven by China and India.
Download Exclusive Sample Of This Premium Report: https://market.us/report/global-mining-chemicals-market/
Key Market Segments:
By Product Type
Grinding Aids
Frothers
Flocculants
Collectors
Solvent Extractants
By Mineral Type
Base Metals
Non-Metallic Minerals
Precious Metals
Rare Earth Metals
By Application
Mineral Processing
Explosives and Drilling
Water and Wastewater Treatment
Others
DORT Analysis
Drivers
The rapid growth of construction, automotive, and electronics industries is pushing up the demand for metals, increasing the use of mining chemicals.
Declining ore grades are making extraction more difficult, leading to greater use of advanced chemical reagents.
Technological innovation in mining operations supports the use of more efficient and eco-friendly chemicals.
Asia-Pacific’s industrial expansion, especially in China and India, is creating massive demand for mining inputs and chemical treatments.
Opportunities
New mining activities in Africa and Latin America open fresh markets for chemical suppliers.
Eco-friendly chemical formulations are gaining popularity due to environmental rules and sustainability goals.
Acquisitions, like Orica’s purchase of Cyanco, offer firms the chance to expand geographically and diversify.
Adopting smart chemical dosing systems and digital control can help boost process accuracy and reduce waste.
Restraints
High transportation and handling costs for specialized chemicals can reduce margins.
Strict regulations around chemical disposal and environmental impact increase operational complexity.
Volatility in commodity prices can slow down mining activity, which affects chemical demand.
Smaller players face stiff competition from major chemical providers with global reach.
Trends
Eco-friendly reagents are being developed to lower environmental harm during mineral processing.
There’s a shift toward custom chemical solutions tailored for different ores and conditions.
Mergers and acquisitions are shaping the competitive landscape and expanding service offerings.
Digital tools like automated dosing and monitoring are being integrated into modern mining sites.
Market Key Players:
Maschinenfabrik Bernard KRONE GmbH & Co. KG
Berry Global Inc.
RKW Group
Trioworld
Joachim Behrens Scheessel Gmbh
Rani Group
Coveris
Shandong Longxing Plastic Film Company
BSK & Lakufol Kunststoffe GmbH
Groupe Barbier
GABRIEL-CHEMIE GROUP
IRIS Polymers
Bialpak
DUO PLAST AG
Silopak
XINJIANG RIVAL TECH CO., LTD
Conclusion:
The mining chemicals market is entering a strong growth phase, with demand increasing due to deeper mining operations, stricter environmental rules, and rising metal consumption. The market is forecast to reach USD 20.3 billion by 2034, with grinding aids and mineral processing chemicals making up the bulk of sales. Base metals continue to be the primary focus, and Asia-Pacific remains the key growth region.
The mining chemicals market has challenges such as chemical costs, logistics, and regulatory hurdles remain. Opportunities lie in sustainable solutions, smart technologies, and expanding into new regions with rich mineral deposits. Companies that can provide efficient, eco-friendly, and customized chemical solutions are likely to succeed in this evolving market. Overall, the future of mining chemicals looks promising as the industry leans into innovation, sustainability, and smarter operations to meet the growing global demand for minerals in an environmentally responsible way.


